Unlike salaried employees, business owners are deeply tied to their companies through day-to-day operations, personal wealth and ongoing legal obligations.
Stepping back isn’t an eleventh-hour admin task. It requires an early, coordinated strategy across both your business and personal affairs, according to MV Law partner Massimo Di Maio.
“When you retire, as an employee, you just basically walk away, and you can move on. But businesses cannot just be left like that without proper consideration,” he says.
Effective exit planning rarely means picking a target date and working backward – the groundwork actually starts on day one. Even a sole trader can’t simply lock the doors without wrapping up loose ends, from commercial leases and asset sales to product warranties and consumer guarantees.
“Start the business with the view of what you want to do when you want to exit the business, because thinking about retiring for one person is one thing, but when you have two or three shareholders involved, it becomes more complex,” Massimo says.
When co-owners are in the picture, clear ground rules keep the business running smoothly if someone decides to leave.
A solid shareholder agreement should give existing owners the right of first refusal on a departing partner’s shares, preventing an incompatible outsider or competitor from buying in, while setting clear rules for how the business will be valued so exits don’t end in bitter disputes. Getting this right takes teamwork between your legal, accounting and wealth advisors.
Over the years, most company directors tie their own finances to the survival of the business. Walking away means untangling those personal risks.
“In the course of business, business owners would have signed plenty of contracts with loans or, if they’ve entered into a lease, they would have provided personal guarantees to landlords,” Massimo says.
“They need to get released from those personal guarantees.”
Alongside getting formal sign-off on leases and loans, Massimo routinely checks outgoing businesses for lingering liabilities that could come back to bite, such as unpaid employee leave, outstanding warranties and past claims.
Your industry can also dictate how early you need to start.
In construction, for example, heavy machinery and long-term building defect liabilities require a much longer runway to wind down safely.
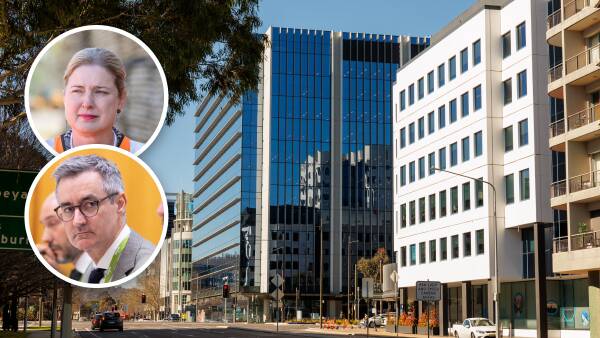
MV Law partners Massimo Di Maio and Tanya Herbertson often team up to bridge the gap between commercial business succession and personal estate planning. Photos: MV Law/Michelle Kroll.
A good exit plan also prepares for the unexpected, like sudden illness or death — the critical crossroads where business succession meets personal estate planning.
As fellow MV Law partner Tanya Herbertson explains, many owners mistakenly assume their standard will covers their business.
“One fundamental error business owners make is assuming a personal will dictates corporate or trust assets,” she says.
“Personal assets can be dealt with in the will, but assets that belong to a company or a trust can’t necessarily be bequeathed via a will. Instead, we need to look at control of those entities.
“If a sole director is incapacitated, the company can grind to a complete halt, nobody is authorised to run operations, execute contracts, or access bank accounts. Similarly, with family trusts, business owners often overlook who holds the role of ‘appointor’, the person with ultimate power to hire and fire the trustee. Without naming a successor appointor in your estate planning documents, control of the trust’s assets can end up contested or stranded.”
To keep the business from freezing up in a crisis, owners should put a company power of attorney in place early, alongside their personal enduring power of attorney.
Just as importantly, your personal estate plan needs to match your business agreements, like shareholder, partnership, or trust deeds, so they don’t pull in opposite directions.
“If there is a contradiction between a shareholders’ agreement and estate planning documents, that would be a disaster,” Tanya says. “You want to make sure that you’ve identified what it is that your client actually wants to achieve and make sure all the documentation flows in that same direction.”
For multi-generational family businesses, handing over the reins takes more than just legal paperwork. It requires an agreed-upon roadmap, often set out in a family charter, that balances family harmony with commercial reality.
Navigating these overlapping demands requires coordinated input across multiple legal disciplines.
“When clients come in, if they’re doing their personal estate planning and their business succession planning, we’ll often use a different expertise within our firm and work together on it,” Tanya says.
“That ensures everything’s covered properly, because there are a lot of moving parts when a business owner retires.”
For more information, visit MV Law .