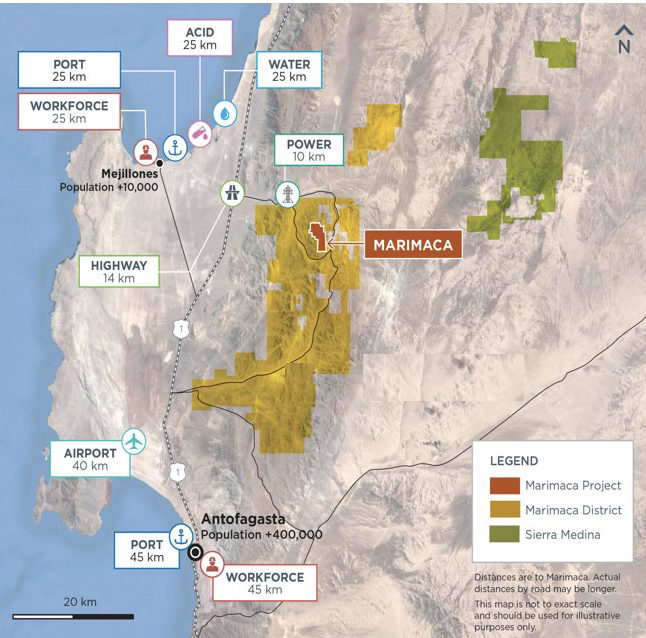
Marimaca Copper’s (TSX: MARI; ASX: MC2) definitive feasibility study (DFS) confirms the Chilean oxide project at the low end of capital intensity among South American copper builds.
The DFS, released on Monday, outlines a 13-year, open-pit, heap-leach copper project near Antofagasta, northern Chile, producing copper cathode at an initial 50,000 tonnes per year. At a long-term copper price of $4.30 per lb., the study returns a post-tax net present value, at 8% discount, of $709 million and a 31% internal rate of return, with 2.5 years’ payback.
Marimaca pegs pre-production capital at $587 million, implying capital intensity of about $11,700 per annual tonne of copper capacity. That is on the low-end of the global scale, according to Locke. On the recent three-month Comex average of $5.05 per lb., the post-tax NPV rises to $1.1 billion and the IRR to 39%.